EPISODE:
Stay tuned after the conclusion of the podcast for additional important information. Subscribe for more episodes connecting macro trends to portfolio strategy and visit PIMCO.com for extensive research and resources.
VOICE-OVER: Welcome to Fixing Your Interest. Today's episode explores aviation finance, an increasingly important part of the asset-based finance universe that helps fund commercial aircraft and support global air travel.
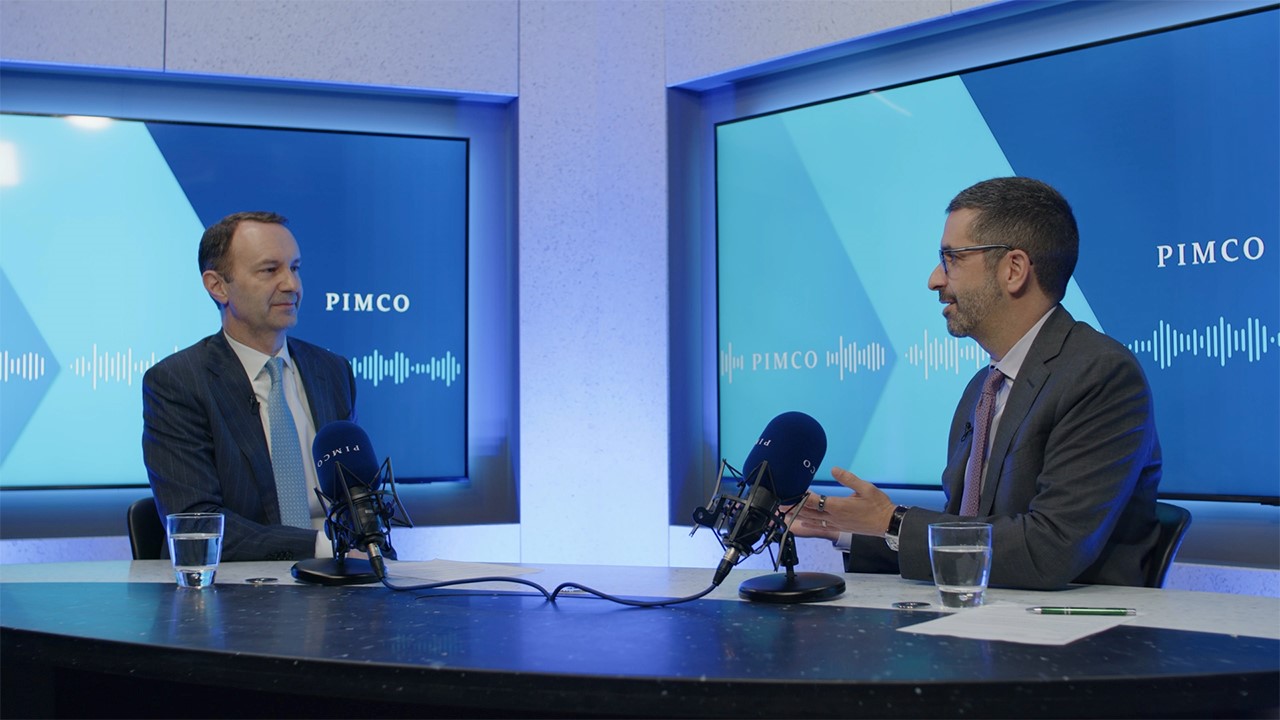
Greg Conlon, CEO of High Ridge Aviation, joins Kris Kraus, Portfolio Manager and co-lead of PIMCO's asset-based finance platform, to discuss how the market works, what's driving the opportunity today, and why investors are paying growing attention to the sector.
They also examine the role of aviation finance within broader private credit allocations, the factors supporting demand for aircraft leasing, and the opportunities and risks investors should consider.
KRIS: Great to have you. Thanks for taking the time.
GREG CONLON: Appreciate it. Thanks for having me.
KRIS: Cover a little bit of the aviation space today for everybody's benefit. Chief Executive of High Ridge Aviation, which you founded, obviously spent a long time at GE prior to founding High Ridge. Why don't you take us through sort of the beginning, what is aviation finance as we think about this market? We've obviously talked a lot about it. For the benefit of the audience, maybe give a bit of background on the sector.
GREG CONLON: Sure. So a little background on myself. As you mentioned, the Chief Executive Officer of High Ridge Aviation, we founded together with PIMCO. Prior to that, I was the Chief Executive Officer of GE Capital Aviation Services, or GECAS. That was the world's largest aircraft leasing company in the world for about 27 years until that business was sold in '21. And then we started working with PIMCO while we were at GE.
So we had a relationship going back then, and as we moved from '21 on to '22, '23, there's a lot of growth in our space, and we can talk about that in a little bit. But we started High Ridge Aviation together with PIMCO in '23. And really the opportunity there, KRIS, was I had the entire senior management team of GECAS available, right? All at the same time, which was kind of an opportunity of a lifetime.
And why we were, as any business you work for over 20, 30 years goes away, you know, you're upset about that for a bit, but then you realize the opportunity you have. And we were all super excited to jump on this. So in '23, we launched High Ridge Aviation with yourselves and, again, founded by the senior management team at GCAS. And today we're over 32 employees, over $3 billion in assets and on our second fund.
KRIS: Nope. Sounds good. And obviously we've had the benefit to work together and have had the experience of working with your entire team. And obviously the quality of the individuals as well as the quality of business is something that we certainly appreciate and comes through day in and day out as we all work together.
Maybe spend a minute or two sort of unpacking, so, you know, this afternoon I may get on a plane, fly from London to Frankfurt or Milan or Paris. I'm sitting in the seat of an Airbus 320, whether that's British Airways, whether that's Lufthansa. Pick a carrier who actually owns that plane. Right. How does it all get financed? These obviously, you know, big capital-intensive assets that maybe help sort of unpack a bit of how this all gets financed.
GREG CONLON: Yeah. I mean, you're right, KRIS, most people don't even think about who owns the airplane, or in fact, they just assume the airline owns the planes they fly. And 20, 30 years ago, about 20% of the world's fleet was owned by leasing companies. The rest was owned by airlines. Today, that number is well over 60% is owned by leasing companies. And in particular, the Airbus order book, in some cases almost 80% owned by leasing companies. So you're seeing a lot of growth in the leasing space.
And we do that, and the airlines do it for a couple of reasons. As you mentioned, these are not inexpensive machines, right? Narrow-body aircraft are $60 million each and wide-body aircraft, you know, the ones with the two aisles on it. Those are $150, $160 million each. So this is a high-capital-intensive business for airlines. And leasing has become increasingly more efficient for them to use. How does it work, right? How does an airline finance aircraft as they, as they deliver, right?
KRIS: Someone's paying for this, someone's paying Airbus or Boeing. And so that money's coming from—
GREG CONLON: So you think about it this way. About 70% of the world's aircraft are ordered by airlines from Boeing and Airbus, and then leasing companies order about 30% of the aircraft, and they order them on spec. So they buy them in advance, and they don't know who the leasing, who the airline's going to be, but the airlines back to the airlines. So those, that's 70% of the market they ordered as it comes, and they order years in advance, right?
You can't get these aircraft in a year. I mean, you're currently sold out till early into the next decade to get another airplane. So they buy these several, they commit to these aircraft years in advance, and as they get closer to delivery, they decide on how they're gonna finance it. They could pay cash, they could use debt, or they could do a lease.
KRIS: Right.
GREG CONLON: And so what Ridge does, among others, is we'll talk to those airlines about those deliveries coming and we'll agree in advance, several months in advance, when this airplane delivers, we will buy the aircraft the second it delivers from Boeing or Airbus and immediately lease it back to them.
And these leases are typically eight to 12 years, what we call triple-net leases, right? They're fixed-rate US dollars, monthly in advance, hell or high water leases, right? They can't break them, whether there's a COVID, they can't break them, whether there's another SARS or what have you. So they're very sticky cash flows, which is why a lot of investors kinda like this product.
KRIS: And do you think that, that you sort of big complex assets, you and I have been to Toulouse together, we've been to the production facilities at Airbus. I think the market overall might sometimes ask, well, why don't they just ramp up production and sort of close the gap in terms of, you know, time from today to 10 years out to sort of meet that demand.
What are your perspectives on that? I mean, again, we've been there together. We think this isn't just a production facility that you can easily ramp up, right? Just given how complex these assets are, the regulation around that. Maybe speak a bit about that in terms of just how that supports the opportunity set that we're looking at.
GREG CONLON: Right. So you're in 2017, 2018, the world was roughly balanced in terms of supply and demand, in terms of announced production rates, what the airlines ordered. You had COVID where you had a grounding of a Boeing product for two years, that was 500 airplanes that were never built. You had a reduction in supply of aircraft just because Boeing and Airbus were reducing production during COVID and a lot of airplanes that were supposed to be built never were. And so we find ourselves today in a market where almost 22% of the world's fleet was never delivered. That's about 5,200 airplanes that were supposed to be flying today that aren't.
KRIS: That's a big number.
GREG CONLON: They said it's a big number. There's only around 23,000 Boeing Airbus jets flying, give or take a few today. Right? So you're over 20%. We're under supply now, and I think people maybe watching this and fly, like you and I do, realize how full the planes are. And nobody gets upgraded anymore. The planes are full. So back to your question, guys, isn't this a great problem to have?
Just build more planes, right? Right. Well, as you mentioned, you know, these planes are incredibly complex machines. I mean, there's millions of parts. In a wide-body aircraft, the supply chains are as long as you can imagine. And also the engines are very complex to build, and so they would like to build 'em as fast as they possibly can.
And they are, it's just the nature of that shortage is really gonna express itself for the next 6, 7, 8, 9 years. Where you're gonna be, the world's gonna be short on airplanes. And so from an investor thesis, it's a good asset to own because your lease rates are higher, your renewal rates are higher, your residuals are higher. And as much as they'd like to reduce that, and trust me, Boeing and Airbus would. And their shareholders would. They're, they're frankly going as fast as they can.
KRIS: Right.
KRIS: Right. No, and so, from an investor's perspective, right, that's providing sort of that upward support that we see in terms of lease rates, right? Airlines don't necessarily just have the benefit of picking and choosing.
They almost have to take what the market's willing to offer them, whether that's sort of the new production coming off the line, or maybe even talk a bit about sort of the secondary market activity that you and the wider High Ridge teams, you know, see day in and day out and participate in, and how that's been supportive just to the overall investment thesis.
GREG CONLON: Sure. So we've seen a lot of pickup in not only lease rates because the aircraft are scarce. And so airlines that ordered airplanes that were supposed to deliver last year, this year, next year, they're not delivering for four or five years later.
So they have to not only lease more planes from leasing companies, but they also have to extend the airplanes that were coming off lease that they originally planned to return. So you're, as an investor, you're seeing a little pickup in not only lease rate today, but you're also seeing a pickup in renewal rates.
KRIS: Yep.
GREG CONLON: So in a normal market, give or take a few, about 60% of aircraft extend their first leases. Now we're seeing that's around 94%. Okay. Because there is no replacement. So from an investor perspective, you're, you like renewals because you don't have transitions.
KRIS: Right.
GREG CONLON: Transitions is naturally downtime. You have to reconfigure the aircraft. It's all planned, but downtime and expense that you don't have, it's much easier to extend an aircraft for an airline than it is to move somewhere else. And we're seeing a lot of that, again, unprecedented levels of renewal rates.
And which is driving some of the investment thesis. And with any good market dynamic, there becomes cautionary things that you must be aware of. And one of the things we pay a lot of attention to is asset values have gone up. You have to be very careful on your entry point. And I think that's makes a difference when you have a very experienced, seasoned team who's bought hundreds and hundreds of airplanes over decades, we know what these asset values long-term trade for.
KRIS: Right.
GREG CONLON: And we're very cautious about not chasing the market today and making sure we underwrite and stay disciplined in our approach. And I think that goes back to our relationship maybe five, six years ago between GE and PIMCO had a very similar DNA about how we underwrite deals. We spent a lot of time on the down, almost obsess on downside risk versus upside. And so I don't know if we're enabling each other on that, but I think at the end of the day, it provides a level of comfort for folks to know that, you know, we're not chasing market here. We're doing good fundamental underwriting. Right.
KRIS: Right. Well, and I think that you bring up a good point. I think that was one of the attractions, if I go back to, you know, the early engagement that we all had together in terms of how you and the team think about different states of the world, right?
It's an asset class that's been around for many decades. We've been through different cycles in the past. You know, the dynamic today in terms of that supply-demand imbalance and that more secular shift in terms of airline operators no longer being the owners of the planes and pushing that out into the leasing part of the market, you know, has real appeal.
And as we think about just in general, aviation finance, alongside a wider potential opportunity set that sort of monthly cash flow, strong income-producing asset, it's got obviously the hard asset, the metal as we sometimes say within the team, you know, is obviously I think provides that sort of level of resilience that we, at least from the PIMCO side, and I think, you know, on behalf of investors in the market, you know, find the asset class to be so attractive there.
Maybe talk a little bit about sort of what sort of economics are we seeing in the market today? Maybe kinda walk through how we go about generating returns. What, when you think about lease rates, you think about the way in which maintenance reserves play a part in that, and maybe too just the overall active management that you and the team have, right?
All of that experience from your time at GE as well as in the years here with the founding of High Ridge, how you're going about generating that alpha, right within the asset class.
GREG CONLON: So you bring up a couple interesting things there. One is the nature of these leases, their long-term leases, eight to 12 years, they're payable monthly in advance US dollars. Fixed rate. So you have a steady cash flow associated.
KRIS: That's whether it's in the sky or on the ground, you've gotta make it— Yep.
GREG CONLON: A hundred percent, right? And so that makes the aircraft, you know, tradable in terms of the cash flows are solid. People know what they're going to get. You're also bringing 'em another point. There's generally two types of leases.
There's leases where for better credits there's two types of cash flow component that comes in on a lease, your monthly rent. But the airline also has to pay you for maintenance. They burn off the airplane during its term. So think about it like a car lease where you have a monthly car payment, but they also have a per mile or per kilometer charge, at the end. It's similar on an aircraft.
KRIS: Right.
KRIS: And then a lot of that focuses on the engines.
A lot of it's in the air [UNCLEAR] on an engine operating, you know, 11, 12 hours a day.
GREG CONLON: Yeah, a hundred percent. Right. They, they fly 11, 12, 14 hours a day every day for years, and those engine components need to be replaced and the entire engine component can be replaced nose to tail. Unlike an airplane, you don't replace a fuselage. But the, the engines consume a lot of the, its maintenance burn.
So the better credit airlines at the end, I buy a brand new, I'll lease it to you, Kris, and in 12 years later you give it back to me. And when I said you burned 80% of the time off the engines, you know, you owe me 20 million. The airline says, fine, the weaker credit airlines would love to do that deal as well.
But you're taking more risk as an investor that they default right prior to that point, and then they give you the airplane back. You don't have that maintenance cash flow associated with it. And the airline says, I'm really sorry, but we died last week. That's the end of that. Right. For those type of transactions, we'll do what's called cash reserve deals. Right? So in addition to the monthly rent, they also owe a monthly payment equivalent to the maintenance burn. Right?
KRIS: So, that obviously helps mitigate that risk,
GREG CONLON: It fees that risk for investors that come into this space. And so you, you have some pretty steady cash flows associated with this, but at the end of the day, you need, you need to, you know, these are high capital items.
Their typical unlevered yield is around, call it nine to 10% these aircraft. The good thing about these is, they're cash flowing day one. And when we buy an aircraft, it's on lease, or we put it on lease right away.
And then sort of the key in this space is eventually for investors, you've gotta harvest the capital and return their capital. And these are great that they're eight and 12 year leases, and some investors may want to go eight and 12 years a lot like less than that.
And so this is where the experience of the team comes into play at GECAS, we were, just to put it into context, we were originating anywhere from five to $8 billion a year of aircraft. And then we were selling between two and 4 billion every year. We're selling 150, 160 aircraft every year. I mean, one, every 50 hours we were—
So you bring that experience to a fund table where we're much more focused and we have maybe 50, 60 aircraft in a fund, roughly a third of what we sold in a year previously. But that team now is very efficient at harvesting this portfolio in a timely manner.
We, we put portfolios of, of 10, 12 airplanes together, we'll go to a market, right? We'll do an RFP and we make sure that the bids come in and, and we're getting good execution on those aircraft. And so we have a lot of experience in selling the aircraft and making sure that you're selling them efficiently to the right buyers and, and kind of, again, minimizing that downside risk on the investment thesis to kinda really target that mid team return.
KRIS: Yep. No, that makes sense. Yeah. And we've seen, obviously, you know, in the markets today when you've got that strong sort of hard asset coverage, you've got an income producing asset they tend to finance, you know, quite well.
And we're seeing that obviously with capital markets having come back for the asset class and, and obviously some of the things that we're able to negotiate from the PIMCO side on behalf of High Ridge in terms of from the bilateral financing we've been able to, to arrange. So all, all pointing in the right direction.
GREG CONLON: And that's been a tremendous asset to this partnership for the High Ridge team is the ability of the PIMCO team to efficiently finance these aircraft as you mentioned there. They're not inexpensive.
KRIS: No.
GREG CONLON: And managing the right side of the balance sheet, managing the liability structure, getting efficient debt terms, getting long-term warehouse facilities that allow the fund to build patiently. Rather than quickly, or again, defeating that downside risk. We don't have refinancing risk in the fund. We're match funding.
Everything we do here and when the PIMCO machine comes in and can provide that support to and allow us to really do what we're good at is buying the assets. You're kind of, you're getting the best of both worlds. I like to think. And it's been exceedingly successful for us.
KRIS: Yep. No, appreciate that. I, yeah, it's, it's been a great partnership, you know, all around. And obviously I look forward to continuing to work together with you on that. Greg, let's spend a minute talking about relationships.
Obviously you spent a number of years at GE as a leader in this industry, you've brought a lot of that expertise to High Ridge. But I also think one of the important things you've brought and the wider team has as well, the relationships in this space, in this industry.
We obviously PIMCO we operate in markets, private markets, public markets, sometimes markets are trading, you know, a basis point this side or that side. As we interact and as we source risk and underwrite risk and finance risk with High Ridge, I continue to be impressed by your ability to lean on those relationships to source attractive risk where maybe we don't always have to be the best price.
GREG CONLON: Right.
KRIS: Can you talk a bit about that? And I also want to maybe a two part question ask you a bit about just, you know, on the sourcing side as well. I mean, I see it through the pipeline, the different opportunities you're able to bring into the room to discuss and underwrite how you're able to tap into that network that you've obviously built up over a number of years.
GREG CONLON: Right. So it is very much a relationship business. There are only two aircraft manufacturers in the world. There are three aircraft engine manufacturers in the world. There are maybe give or take a few or 300 airlines in the world. 200 of 'em are probably potential clients. You're gonna talk to all of them, 50, you're gonna be your sort of kind of go-to, and then there's gonna be those five or six airlines where you are just gonna be that repeat business.
Very good relationship with 'em. This is a long-term industry. Airlines have long memories. They remember things that, you know, you did that they didn't like. So it's very much, it's not a one fund and done industry because it's very hard to originate these transactions. We were one of the largest buyers of aircraft in the world for many, many years.
And we, there's not a transaction that we don't see in the current market. From both the aircraft manufacturers calling us and say, oh, we have an opportunity here, or the airlines that we're constantly talking to. So we have a very wide mode of transactions we see, and we bring that wide mode to a much more focused investment thesis.
And I think that, that helps us bring more value in terms of how we can underwrite transactions. But it's a competitive market out there and the say-do ratio matters. These transactions have a long gestation time. So, you're not buying securities outta Bloomberg terminal here, you missed one there [. This is six months to do a transaction. And so your counterparty or your airline, if they know you and they know you'll close and they know you'll work with 'em five years from now and something needs to be changed, that's worth something to them.
GREG CONLON: Yeah. And so they won't trade it down to the last basis point on that. And you earn that reputation over many, many years. And, and we've been able to kind of capitalize that and as we build out the funds with, with you and PIMCO. So those relationships are key to differentiate us and, and also it helps us kind of defease risk. You know, there are downsides in investing in any asset class, including aviation.
KRIS: Right.
GREG CONLON: There are things that go wrong. People read about bankruptcies all the time. I mean--
KRIS: You've seen that.
GREG CONLON: Airlines are, it's a really tough business to do an airline. You're semi regulated on the revenue side, you're unregulated on the cost side, and most of your customers hate you. And it's difficult to make money. We see that a lot where we think…
KRIS: Super thin margins in the airline.
GREG CONLON: It's tremendously thin margins.
GREG CONLON: It's super competitive. They're heavily regulated. It is not a business model that, that enjoys leverage. And you have very asset heavy of equipment that you need in order to finance that is challenging. So you can easily enter into transactions here. And, and what we see a lot is we see other investors that come in and just love credit.
They love airline X because it's a flag carrier of country Y. And I want that exposure. What they don't pay attention to is the asset they bought is not widely flown by the world, or it's very uniquely configured, and it's going to cost millions to reconfigure it. Because sooner or later that wonderful airline that you leased to and didn't make very much money on, it's going to give you that airplane back.
And you're gonna find that it's quite difficult to move that and get a return that works for investors. And so where we try to defease that risk is less about, you know, chasing the best credit in the world. And it matters, obviously, but more about underwriting the asset. Because at the end of the day, this is asset backed finance. And we're not financing free cash flow for an airline. We're buying an asset that we own and leasing it to an airline.
If there is a default, we take it back, we redeploy, we move it somewhere else, and you defeat your risk that way, but you have to buy the right asset at the right price. And so we, there's ways where we try to defease that downside risk. And, it's less about credit than you think. It's really more about knowing that asset. And you just learn that over, over experience.
KRIS: Right. And I guess as part of the underwrite, you know, thinking about, well, if we did have to take the keys back, so to speak, where could we go with that?
GREG CONLON: Sure.
KRIS: And maybe that feeds into a bit to, as you think about, let's call it portfolio construction, which models do you want to have in the portfolio? Which models that if you had to take back and reposition somewhere else in the world, you know, you could just given the demand for that type of aircraft.
As well as maybe some parts of the market where you look at it and say, it might be great to fly on that particular model of aircraft, but I'm not sure I actually wanna be an owner of that because no one else would actually potentially take that on. Should I ever have to take the key?
GREG CONLON: That's absolutely right. So we're, as we build out the portfolio, you're obviously mindful of managing exposure not only in terms of country exposure, but jurisdiction and credit and asset type. And we try to focus primarily on newer technology, narrow-body aircraft, I think one aisle.
Three seats on the right, three seats on the left. And we love wide-bodies too. And airlines love wide-bodies. The big guys, the seven eight sevens, the three fifties. They make a ton of money flying them. They're most profitable. They have the super exotic business class that you wish you were flying in, but your company travel policy doesn't let you.
But, and those airplanes are great, but they're significant capital outlays to transition those aircraft. And so it's a different investment thesis if you want to target that. You need to be very confident they're gonna stay there. But we're to in a more, I say focused newer technology, narrow-body, fuel-efficient aircraft.
Again, you're, kind of, you're mitigating your downside because there's just the most number of operators in the world out there. So even if I have a scheduled lease expiry. I have the most number of airlines in the world to call. And those configurations of the airplanes are pretty similar. And so my downtime is short. I can move those in a month. I can spend less than a couple million dollars to move it. If I have a wide-body aircraft, I could have six months and 30 million to move it.
KRIS: Right.
GREG CONLON: So you, there's times and places for both. But for this strategy, I think your best risk adjusted return is really those newer technology and narrow-body aircraft and no insignificant factor because they burn about 15 to 40% less fuel. And in today's market, that matters to airlines a lot.
And airlines operate on a single, single-digit margin business. And when fuel is your number one cost, or your number one, number two cost. 15 to 40% makes a huge difference when fuel's trading elevated levels, which looks like it may be for the next several months. Again, try to defease that downside risk where we can and kind of maximize that outcome for investors.
Where do you see aviation finance fitting in sort of investor buckets in terms of, you heard we're anywhere from we've been called nice things like tactical opportunities. We've been called special situations. We've been called all kinds of things, but knowing, you know, your experience in this space, where do you see this as a natural fit for investors' allocation?
KRIS: It's no, I appreciate you putting the question back to me. You aviation's been around for a long time, right? I think our, you know, initial investment in the sector probably goes all the way back to the late seventies, early 1980s.
It's been an asset class in which the various ways in which you can invest in it have evolved to a place now where, you know, obviously one of the attractions with High Ridge and the space in the sector today is that strong income-producing component associated with that. Right? Many parts of the investible market, you know, may have a relatively low current coupon, but more of a backend-type return.
And there can be, you know, appropriate pools of capital to take advantage of that. But as we think about a lot of our income-producing strategies across private markets and what we're doing in private market vehicles as well as even in public markets, right?
Because there oftentimes can be a securitization angle to what we're doing in aircraft. A lot of it just comes back to how you build that portfolio, as we just talked about in terms of diversification of airline types or model types. An important part of that and what the financing market can provide associated with that, which can be an enhancement to the returns. But it comes back to that hard asset coverage that we like within the sector and that stable lease payment associated with that asset.
And at the returns that we've been talking about here, you know, we find that to be quite compelling, right? And clearly with High Ridge, we've got a great operating partner who understands the market better than others, and who has that, I think too, that active management approach to the sector.
I mean, I see it in all the different ways in which you and the team have been able to generate alpha for the benefit of what we're looking for. And it just continues to pay off day in and day out. So we obviously remain very, very focused on it. And so excited about where we're at today, but obviously even more excited about kind of where we're going and that opportunity set as we go deeper into this market. So, I appreciate the time.
GREG CONLON: Thanks very much, Kris.
KRIS: All right. Good to see you.
GREG CONLON: Good to see you.
VOICE-OVER: Thanks for joining us on Fixing Your Interest as we explored how aviation finance works, what makes it a compelling area of asset-based finance, and the opportunities and risks investors should consider.
Stay with us as we continue to navigate an evolving investment landscape.
For further insights, analysis and resources, visit PIMCO.com.
From This Episode
Kris and Greg explain how airlines access the aircraft they need to grow, why leasing has become a dominant source of financing, and what makes aviation a distinctive segment of private markets. They discuss how aviation finance combines contractual cash flows with hard-asset backing, the supply and demand dynamics shaping the market today, and why investors are paying closer attention to asset-based finance as they seek diversification beyond traditional corporate lending.
The conversation also covers the long-term growth in global air travel, aircraft supply constraints, the importance of specialist underwriting, and how investors evaluate both the opportunities and risks associated with aviation finance.
Key topics include:
- How aviation finance works and why aircraft leasing has grown over the past two decades
- Why more than half of the world's commercial aircraft are now leased
- The role of aviation finance within the broader asset-based finance universe
- How contractual lease payments can generate income backed by tangible assets
- Why airlines increasingly rely on leasing to fund fleet growth
- The supply and demand dynamics shaping the aviation market today
- How aircraft differ from traditional corporate credit exposures
- The diversification benefits aviation finance may offer within investor portfolios
- Why specialist asset management and underwriting expertise are critical in aviation investing
- How investors assess opportunities and risks in one of private markets' most global asset classes
This conversation offers a practical introduction to aviation finance and the growing role asset-based finance plays in supporting the real economy.