EPISODE:
Stay tuned after the conclusion of the podcast for additional important information. Subscribe for more episodes connecting macro trends to portfolio strategy and visit PIMCO.com for extensive research and resources.
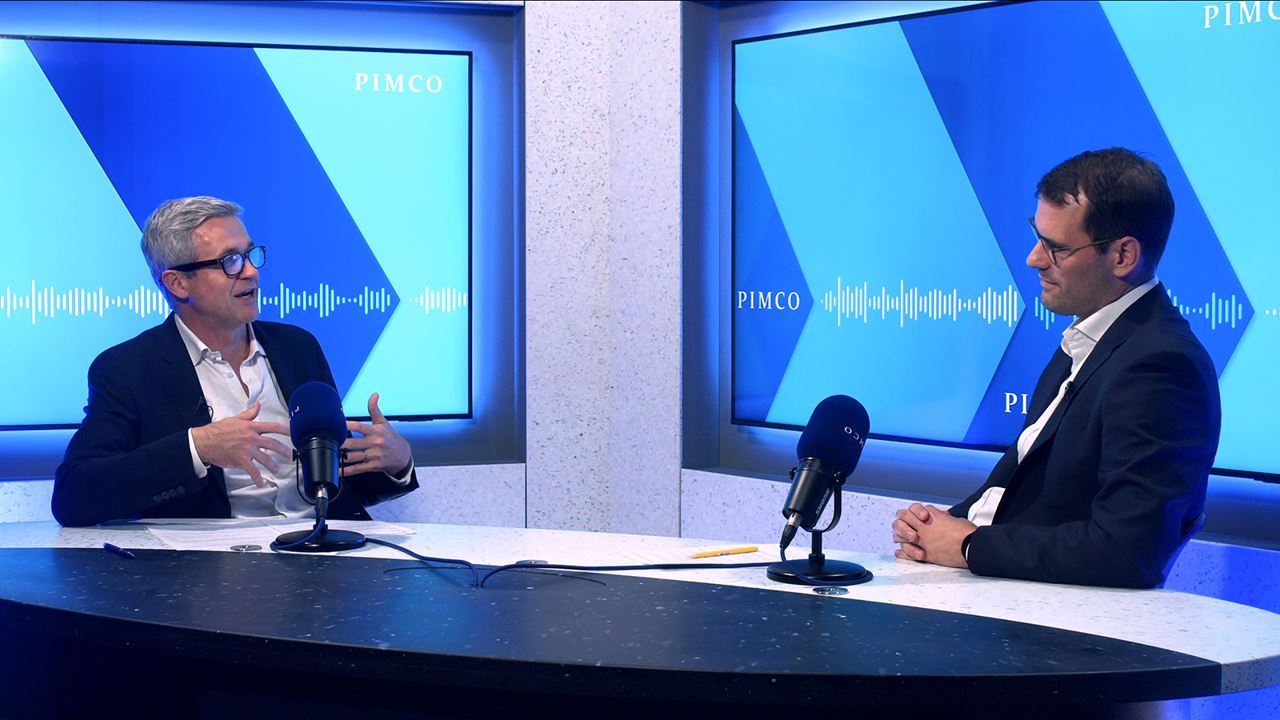
VOICE-OVER: Welcome to Fixing Your Interest. In today’s episode, Lotfi Karoui, Multi-Asset Strategist and Head of Client Solutions and Analytics, and Nidhi Nakra, Credit Portfolio Manager, explore how the AI investment boom is reshaping global credit markets. From the financing demands of the data center buildout, to higher funding costs and growing corporate issuance, the discussion looks at where risks may be emerging, where opportunities are developing across the U.S. and Europe, and why active credit selection could become increasingly important as this investment cycle unfolds.
Nidhi Nakra: Lotfi, welcome once again to London. It's been an unusually foggy two days.
Lotfi Karoui: Thanks for having me.
Nidhi Nakra: Yeah, warm welcome to you. As a credit portfolio manager, the AI capex theme has really dominated spreads, so as such, I think it would be nice to clear the fog on a few of the CapEx questions. Let’s start with the US midterms, what are the implications for the large Democratic congressional majority for the AI CapEx buildout?
Lotfi Karoui: Well, I guess prediction markets didn't wait for the election to happen to kind of start pricing in some of that. But the most immediate implication is that it probably introduces a serious friction in this AI infrastructure buildout.
It does make permitting somewhat more complicated than initially, you know, anticipated. The question is, is that friction going to slow down the pace of this CapEx cycle without necessarily impacting its ultimate size, or will it kind of change both? My view would be that it’s probably more likely, that this is just a change in the pace of the buildout without necessarily impacting the ultimate size.
And so, in other words, the destination is the same. The journey might take a little longer. And that has plenty of implications in terms of relative value performance, in terms of where actually value in that AI infrastructure buildout is accrued. But size, I think, is unlikely to change. You know, the pace of the buildout will likely slow down a little bit.
And if you go back, you're right. AI as a theme has been a major driver of relative performance in the credit markets. And if you go back to the last 12 months, I think the reason why AI has been such a dominant driver of performance in corporate credit is because of the interaction between CapEx and supply. Today, four of the five hyperscalers, are essentially negative free cash flows.
And so the reliance on external funding to continue to sustain the current pace of CapEx is really critical. And I think credit has been kind of caught, or at least the AI ecosystem in credit has been caught in this negative interaction between CapEx and supply, because every incremental new dollar of CapEx, there is probably a decent portion of that that is funded in debt.
If you slow down CapEx, you also slow down supply, and you make that pipeline on the margin, you know, a little more predictable for investors. And so for some parts of the AI ecosystem, this is probably good news. And I'm talking from a credit perspective here, not necessarily the equity perspective.
Nidhi Nakra: Interesting. So your expectation would be more rather, you know, slower buildout rather than less CapEx. And specifically for the US, right? So what does this mean for the rest of the world? Is that greater?
Lotfi Karoui: I mean, if you have to reroute some of the building, you know, outside of jurisdictions that are somewhat less friendly towards AI, then I think the rest of the world might, on the margin, benefit from that. I'm thinking Europe. Canada is another example, you know, abundant land, great, you know, great system, etc. I would keep space, but I would just keep in mind one thing, which is permitting is one friction. But there are other constraints. I think the other major constraint to the buildout is the grid system, power, energy, etc. And so I would keep that in mind in those conversations about potential rerouting because, you know, it's not like energy is abundant in the rest of the world.
I mean, Europe is is a good example. Obviously, Europe is a net importer of energy. And so that ultimately puts the brakes on how much you can relocate, which is why I said initially that this is probably a catalyst for a slower pace without necessarily changing, you know, the outcome. And by the way, rerouting doesn't happen overnight either.
You know, these are sort of decisions that are made over multiple quarters, maybe years. But, you know, power is the other constraint we need to keep in mind, too.
Nidhi Nakra: Yeah, I think that's right. And the investment in Europe already been taking place. Obviously, it's relatively concentrated. I think about two-thirds or more of the planning in Europe is concentrated around five cities.
So there's Frankfurt, London, Amsterdam, Paris and Dublin, affectionately known as FLAP-D. And I think both of us know that Europe is, from an innovation sense, a lot more than just five cities. So there is quite a lot of catch-up to do in Europe and, and therefore opportunities, where we know that in Madrid and Milan, you know, they're working on more data center planning, and then some of the Nordic countries are energy sufficient.
You know, to your point about energy, or France as well.
Lotfi Karoui: Yeah, I think that's got to be the key differentiator, really, in terms of the ability to attract that marginal dollar into the buildout. And I would use that same argument for emerging markets, too.
They could benefit, too, subject to that sort of energy power constraint.
Nidhi Nakra: So let's move on to the financing aspect of this rather large CapEx build. So we have had high policy rates and interest rates for about four years now, and major central banks are hiking, and add to that, in Europe, yields, particularly in France and Italy, have risen. So what is the impact of these higher funding costs on the debt of the build out?
Lotfi Karoui: Well, let's unpack that a little bit because, yes, you've seen a pretty significant reset higher in global yields, you know, US and the rest of the world. But I would say the drivers of that backup in yields were different, actually, across both sides of the Atlantic. I mean, in the United States, it was mostly a real yield story.
If you decompose your nominal ten-year yields into real yield, so inflation-adjusted, and then breakeven inflation, which is your compensation for inflation risk, really the vast majority of the move higher has been driven by real yields. That's really important because that tells you that the primary driver of that backup has been actually a reset in growth expectations, at least before October.
You look at Europe, if I zoom in on markets that have an active, you know, inflation sort of bond market, like euro or sterling, what you see is that the picture has been more mixed. You know, it's been roughly 60/40: 60% in real yields, 40% is a repricing of inflation expectations. That is a somewhat less friendlier backdrop.
And so I get asked this question all the time, which is, how come risk assets digest that, up until early October, the backup in US yields so well? I think the answer is because the drivers of the backup always matter more than the backup itself. And in this case, the drivers were actually a reset of growth expectations higher.
Now fast-forward to today. What happened in October? A major selloff in tech stocks and probably a reset lower in those growth expectations. Duration did what it was supposed to do, which is rally and give you that protection in a multi-asset portfolio. But here again, the rally was driven by the real yield component, which again kind of confirms that, you know, growth is kind of in the driver's seat a little bit.
Nidhi Nakra: Yeah, I agree. So what would you say these higher yields, coupled with that new, you know, return of the correlation to equities, means for portfolio construction?
Lotfi Karoui: Well, there's a number of implications. The obvious one is that the ability of fixed income to give you income, for the lack of a better word, has actually been restored. And so now if you take the dollar market as a benchmark, and you could certainly generalize that throughout the entire G10 universe, but, you know, the base yield is around 5%, give or take ten, ten basis points.
And so the value proposition of high-quality fixed income from a risk-reward standpoint has improved quite dramatically.
I think the other implication of this reset higher in yields is that the ability of duration to protect you in a bad state of the world is dramatically better because real yields are, you know, north of the 2.5% today.
And October was case in point, in my view. You did have a big selloff in the equity market. And to your point, that negative correlation between bonds and stocks was fully into display. You know, bonds rallied, stocks sold off, and you had that sort of embedded protection in a multi-asset portfolio. And so to me, the lesson from that October selloff is that you have to think more carefully about how you allocate that marginal dollar.
You don't have to dislike stocks in order to own bonds.
I think the math looks dramatically different today. You have a starting level of yields that is way more attractive, possibly the most attractive in 25 years. And that, you know, usually bodes well for total returns on a forward basis. But it also gives you that embedded protection in case the cycle ends in an abrupt way.
Nidhi Nakra: Yeah, I couldn't agree more. Very asymmetric levels. And what, you know, this is with regards to portfolio construction, what did the higher yields mean for borrowers?
Lotfi Karoui: Well, someone else is on the other side of that trade, and it's the borrower, right? And so I think this is sort of bad news for low-quality borrowers across the board. I mean, as you know, we're seeing it in the high-yield market, you know, the triple-C part of the market.
So that's the low-quality, you know, part of the high-yield market, has been under pressure pretty much since late April all the way to today. I think one important driver of that has been the reset higher in the cost of funding. But if you built a capital structure in a world where policy rates were close to zero and your running assumption was that the base yield would be, take again the dollar market as an example, between two and a half and 3%, that capital structure does not work in today's world, right? And so the cost of funding, I think, plays an important sort of role there. There are other idiosyncratic considerations, but generally speaking, I think, you know, the ability of low-quality borrowers to sustain, you know, current leverage levels is going to be tested and probably diminished. I think there are other rate-sensitive parts of the economy that this reset higher in rates, you know, will be tested.
I've had a number of clients asking me what this means for the commercial real estate market, for example. You remember the 2023 episode.
Nidhi Nakra: Painfully.
Lotfi Karoui: Exactly. So that was a painful reset higher both on the equity side and the credit side, and both in the US and in Europe.
Sovereign European credit is another area where you've seen pressure. Not entirely due to the reset higher in yields, but somewhat due to it. You know, when you reset yields higher, you do put pressure on sovereign balance sheets that are sort of suffering from the intersection of regrowth and poor fiscal policy. So, you know, that's another area where you, you'll probably see where the bar for normalization is probably quite high.
Nidhi Nakra: Yeah. I guess when we say it's not going to become a credit story, I mean, it's not systemic, but they'll likely...
Lotfi Karoui: Correct
Nidhi Nakra: … Accidents. And we've seen those already. So it becomes quite important, I think, actually, in this…
Lotfi Karoui: To be selective. And by the way, dispersion has been the biggest source of alpha generation. And I think that remains the case.
I mean, I think this is a really important point because when you reset the cost of funding higher, you know, whether it's through the base yield or through the spread component, you essentially reduce incentives to go down in the quality spectrum. All else equal. Again, you know, you can generate a seven, 7.5% on a high-quality portfolio, fixed income.
There's no need to take an excessive amount of credit risk. And so this, in credit jargon, this feels like a decompression environment. All else equal. And I think a lot of it is due to that reset higher on the cost of capital and the base yield in particular.
Nidhi Nakra: Yeah. There's also, well, first of all, the 5 trillion of CapEx over the next five years, in the face of everything you've described and the lack of potential, the attractiveness of the lower part of the capital structure for the wider investors, then who's going to buy this 5 trillion?
Lotfi Karoui: Yeah. I mean, a couple things. I would say, first of all, I'd be a little careful with, like, long-term projections, you know, of CapEx. And so I would take things like one year at the time a little bit. I have great confidence in the 2027 outlook for CapEx, as opposed to a multiyear, multitrillion, you know, type of cycle, because that is based on a set of assumptions.
And those assumptions may or may not materialize. But the biggest one is that there's a little bit of a path dependency. You know, your ability to sustain those level of CapEx depends on your ability to monetize. And so there's a wide range of outcomes. And I think that affects CapEx, too. But let's take it at face value just for the sake of running this exercise.
So the question is, who's going to fund all of this? You know, especially considering the fact that there is a funding gap that the hyperscalers, which are basically the primary source of this CapEx, have. And so if you have a funding gap, well you need to rely on external financing, and you do that either by going to the equity market or debt markets, there aren't that many options for you to do that.
I really think the better question is at what level, you know, that sort of $5 trillion CapEx, which will translate into a couple of trillion dollars of debt supply, will clear. And I like to look back at the last 12 months as a benchmark. If you look back at the last 12 months, this AI supply shock into debt markets has actually been absorbed at its source.
So far, it's been absorbed via wider spreads for that AI ecosystem itself, as opposed to the broader corporate credit market. I think for the next 12 months or 18 months, despite the friction that is introduced in permitting, it's very reasonable to expect the next wave to possibly be at least as large, maybe larger, faster. It'll probably come in more flavors across structures.
And so how would that be cleared? Probably with some additional buildup of risk premium. Now, the difference, I think, between the next wave and the one that we've just experienced is that the next wave will likely become a little bit more predictable. And in fact, if you look at CapEx growth, and I want to emphasize on growth, not the absolute number, CapEx growth is already projected to slow down a little bit.
So that second derivative in CapEx is going to decline a little bit. And if CapEx growth slows down, your issuance pipeline becomes a little bit more predictable. And as an investor, you sort of able to assess, to assign a terminal value as to where this is going eventually. But I do think that part of the reason why the past 12 months, you know, had that level of reset in spreads is because the pipeline was actually quite unpredictable.
It was really difficult. I mean, remember, if you look at CapEx consensus expectations for '26, where we are today versus where we started the year, the number more than doubled, basically. And if that number doubled, that means that supply expectations probably doubled, too. I think next year you feel better, and in 2028 it will likely get even more predictable. So we're not too far from the tip of the mountain, I guess, if you will.
Nidhi Nakra: Yeah, I think it was a fair point about predictability. And also, I guess the point we're making is that if a year or two down, which is far away, but if this is still happening, it's because, and the equity market…
Lotfi Karoui: Would allow it to.
Nidhi Nakra: Exactly. The companies would have shown some monetization.
Lotfi Karoui: And by the way, they did, even though, third quarter earnings season feels like it was ages ago, but it just ended actually two weeks ago. But what are the really important takeaways from that earnings season? That on the revenue side, the numbers were good. I mean, the issue is that the spending side of that equation continues to move faster, which is, you know, why the market reacted the way it did. But on the revenue side, there's clear evidence of monetization already.
Nidhi Nakra: Yeah. So on the question of, you know, spreads clearing, they've been relatively contained, to your point. And there's been this narrative that investors have been selling government bonds to make space for this massive CapEx spending that's coming from corporates. Do you think that's correct?
Lotfi Karoui: Well, you know, that is what's usually referred to as sort of a crowding-out theory, which is the idea, there's this idea that this debt-funded AI CapEx cycle is sort of putting pressure on other parts of the fixed income universe.
And by the way, you hear it when it comes to government bonds, Treasuries or other, you know, government bonds, but you also hear it with respect to other corners of credit markets. Let's start with credit, because that's, to me, that's probably the more obvious crowding-out channel. For now, there's really little evidence, at least on the pricing side, that this AI, you know, debt-funded CapEx cycle is actually crowding out other parts of the universe.
And the best way to look at that, take your investment grade index and then divide it in two universes, AI debt and non-AI-related debt. The non-AI-related debt part of the market has been remarkably stable, actually. You know, spreads are still tight. More importantly, they've been really oscillating within a very tight range.
I think, look, government bonds, whether it's Treasuries or other bonds, have superior liquidity. You just don't buy them for the income. You buy them for the protection. And I struggle to see an AI sort of infrastructure buildout, however big it is, put pressure on a $32 trillion market, which is the Treasury market. Now, the skeptics would say, the counterargument to that is that, you know, try to put, you know, supply of long-dated AI bonds in the context of supply of long-dated government bonds.
And the numbers do look big. I don't disagree. And so from a flow standpoint, it does look, you know, a little big. But I think the, it doesn't fit with the definition of a crowding out, in my view. Usually the textbook definition of the crowding out runs the other way around. It's usually an oversupply of safe assets that puts pressure on the private sector, not the other way around.
Or actually, for what it's worth, we put out a piece, I think, a couple of weeks ago that kind of, you know, runs a little bit of an event study and looks at whether there's any evidence of abnormal returns in the Treasury market around days when you had surprise AI deals, and we haven't found any. Now, that does not mean that the reset higher in real yields is not related to AI.
It is related to AI. But I think the channel through which real yields have gone up has nothing to do with portfolio rebalancing. It's just, you know, investment equals savings identity. And whether you funded the AI CapEx cycle with debt or with retained earnings doesn't really change anything. So you have to be a little bit more nuanced about it.
I think the macro channel is real. Yeah. I mean, when you spend more on CapEx, you mobilize more resources in the economy and real yields go up. But even if you did that with retained earnings, you would have seen the same result. And so it has nothing to do with the funding mix.
Nidhi Nakra: I'm bringing it back to Europe. So we mentioned a few things that could be, you know, Europe could be hamstrung by. One is obviously regulation and the, you know, the varieties in regulation we have across geographies, the space limitations geographically, and then being not self-sufficient in energy, and then also, finally, having, I guess, fiscally strapped balance sheets for the government. Is there low-hanging fruit. What would you be optimistic about in Europe?
Lotfi Karoui: Well, I would say we do have fiscal capacity in Germany. I mean, by and large, you're absolutely right. But if you kind of disaggregate things a little bit, there is, you know, decent fiscal space in Germany, which is still the largest economy in Europe. So that is good news.
So you have the ability to stimulate, if you want to. I would say, look, the silver lining is that Europe has not been at the epicenter of this AI infrastructure buildout. And so that's a bad thing and a good thing. But it could be a good thing in a state of the world where, you know, maybe this friction in permitting ends up being something bigger than just, you know, a temporary slowdown in the cycle.
You know, maybe it could cause a change in the, in its ultimate size a little bit. And so Europe in some ways does provide diversification, you know, for investors that are looking for ways to sort of hedge, you know, the AI infrastructure buildup. That's a good thing. Now, of course, we've seen some issuance in the euro market from the hyperscalers.
But it's not nearly close to the levels that you've seen in the dollar market. So that's one, I think, an interesting point. And in my view, yeah, I think, you know, deregulation and fragmentation, those are sort of structural themes that will take time to unfold. But generally, as a whole, you know, the European economy, you know, could have bigger capital markets, could have deeper capital markets.
So there's plenty of room, I think, to grow those. You know, the laundry list is, however, quite expansive, and there's quite a lot that needs to be done there. But I think if you bring it closer to home, to me, the pitch, so to speak, is, you know, diversification against the AI theme, if that's a concern.
Nidhi Nakra: Yeah. I mean, on the planning side as well, it has been, there's been some acceleration. I know in Spain they relaxed some of the requirements around using renewables. They relaxed non-renewables to 2029. So that's been very supportive for the data center buildout over there. And then, you know, as we discussed earlier, there are regions, France and some of the Nordics, where they are energy self-sufficient.
There's just bright spots. I guess if compute does become scarce and Europe takes longer, and then, I guess, the US is apart, is that overall a positive for credit investors?
Lotfi Karoui: It depends what part of the AI financing chain, or supply chain for that matter, you look at. I think there's no question that if you slow down the infrastructure buildout, you do create scarcity, basically.
And the question becomes, where is the premium for that scarcity value? In my view, I think it's a more positive story for hyperscaler credits relative to hyperscaler equities, because in credit there's a technical sort of tailwind that doesn't exist on the equity side, or not, at least not to the same degree. And that's supply. And so if you slow down CapEx, you slow down supply, etc. I think it's probably a negative for picks and shovels.
You know, semis, memories. It's harder because that is demand destruction that will have to happen. Now, if you slow down the CapEx, that means that you're buying less of whatever goes into the shell, which is the data center. And I think for, you know, further down the chain, neoclouds in particular, it's almost on a case-by-case basis.
You could argue that scarcity means that strong demand is going to linger for a little longer. But that doesn't solve any of the funding issues, and that doesn't solve any of the question marks that have a secular flavor to them. So, i.e., what happens 4 or 5 years from now. But it certainly buys you time. But to me, the key message here is that, yes, you're absolutely right, there's scarcity value that gets unlocked immediately because you got to make that imbalance between too much demand for compute, not enough supply, persist a little longer. Not everyone will benefit from it. To me, the clear winner, or the clear beneficiary, at least in relative terms, is probably high-quality balance sheets in general, because they can afford sort of waiting.
Nidhi Nakra: That was a lot of really interesting insights. Lotfi, so it sounds like high funding costs and regulations will impact companies differently over the next few years, and corporates will have different fates, and therefore corporate selection, or active selection, is going to be important.
And I guess, secondly, Europe is lagging, but there are bright spots and therefore fertile ground for potential opportunities in the near future. Well, thank you very much, Lotfi.
Lotfi Karoui: Thank you for having me it’s been great.
Nidhi Nakra: Good to have you in London. It's a pleasure, as always.
VOICE-OVER: Thanks for joining us on Fixing Your Interest as we explored what the AI investment boom could mean for global credit markets. Stay with us for more perspectives on the forces shaping markets and investment opportunities. For more insights and analysis, visit PIMCO.com
From This Episode
In this episode of Fixing Your Interest, our podcast series for European investors, Lotfi Karoui, Multi-Asset Strategist and Head of Client Solutions and Analytics, and Nidhi Nakra, Portfolio Manager, explore how the rapid expansion of AI is influencing corporate borrowing, credit market composition and investment opportunities across the U.S. and Europe. The conversation examines what higher funding costs could mean for capital expenditure and direct lending, whether Europe can gain ground in the AI infrastructure buildout, and why the next phase of the capex cycle could create greater dispersion across companies and markets.
Key topics include:
- How the AI and data center buildout is changing financing needs
- The impact of higher funding costs on capex and direct lending
- Where Europe could benefit from the next phase of AI infrastructure investment
- How growing AI-related issuance could reshape credit markets
- Why greater dispersion could increase the importance of active credit selection