

This year, the software sector has been one of the worst-performing pockets of the leveraged loan market amid fears that AI would severely disrupt existing business models. The sector’s underperformance has also weighed on the leveraged loan asset class as a whole, given its more than 10% weight in the overall Morningstar LSTA US Leveraged Loan Index.
Software loan spreads tightened over the summer, retracing about one-third of this year’s widening and moving roughly 100 basis points (bps) inside their June wides (see Figure 1). That improvement has partially reversed, however, with spreads widening again since early September. The recovery therefore remains incomplete. The average bid price for software loans is still about 8 points (i.e., 8 cents on the dollar) below that of non-software peers, compared with roughly 10 points in June (see Figure 2).
Figure 1: Software loan spreads have somewhat recovered since their peak sell-off
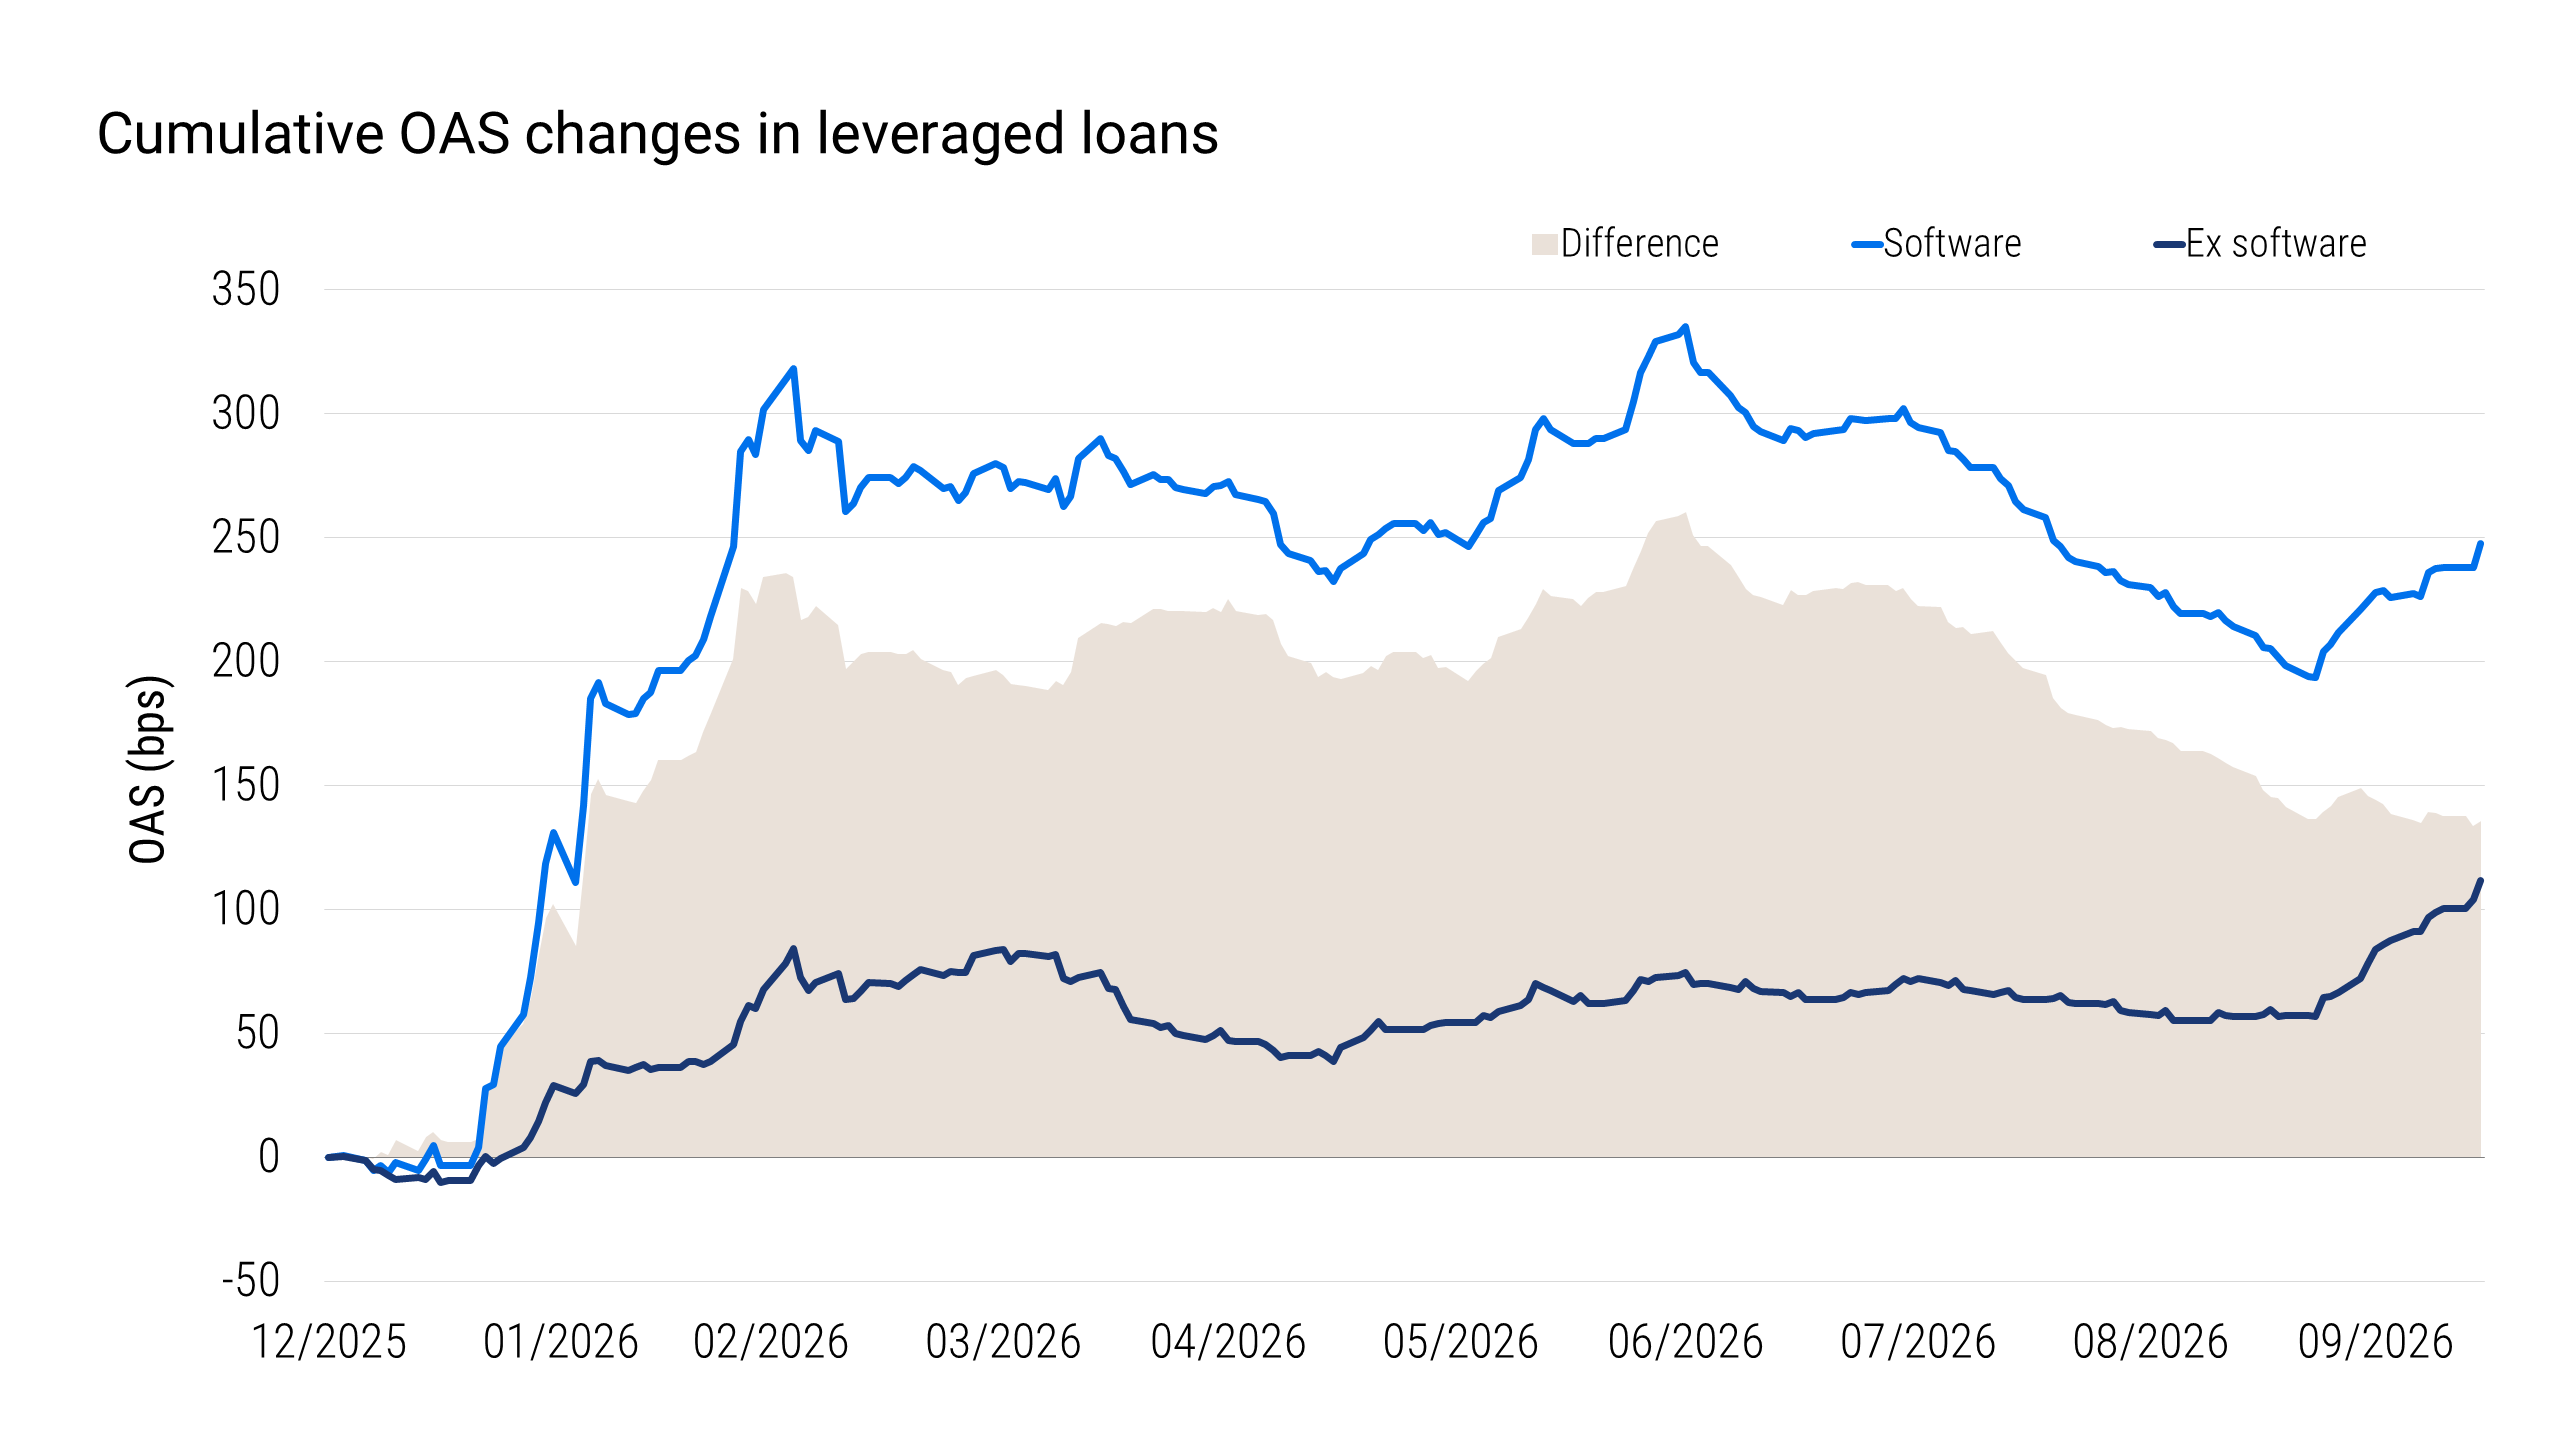
Figure 2: Software’s valuation gap vs. the broader market remains significant

Looking ahead, AI disruption risk and elevated refinancing costs are likely to keep the software sector’s valuation gap versus the broader loan market material. Uneven exposure to these pressures should also sustain elevated dispersion across issuers.
Software equity, software loans: two very different stories
While the spread tightening in software-related loan spreads over the summer appears to be correlated with the broader recovery in software equities, we believe there’s no real causal relationship between the two, and investors shouldn’t take any further recovery in equities as a sign of relief for software loan issuers more broadly.
The reason is that the two universes are vastly different. Some of the largest software firms in the equity market are not only direct AI-related investments, but also investment grade firms with much broader access to public capital markets and other forms of financing, at much lower rates than their leveraged loan peers who don’t enjoy the same kind of financial flexibility.
Key risks still challenge software lending
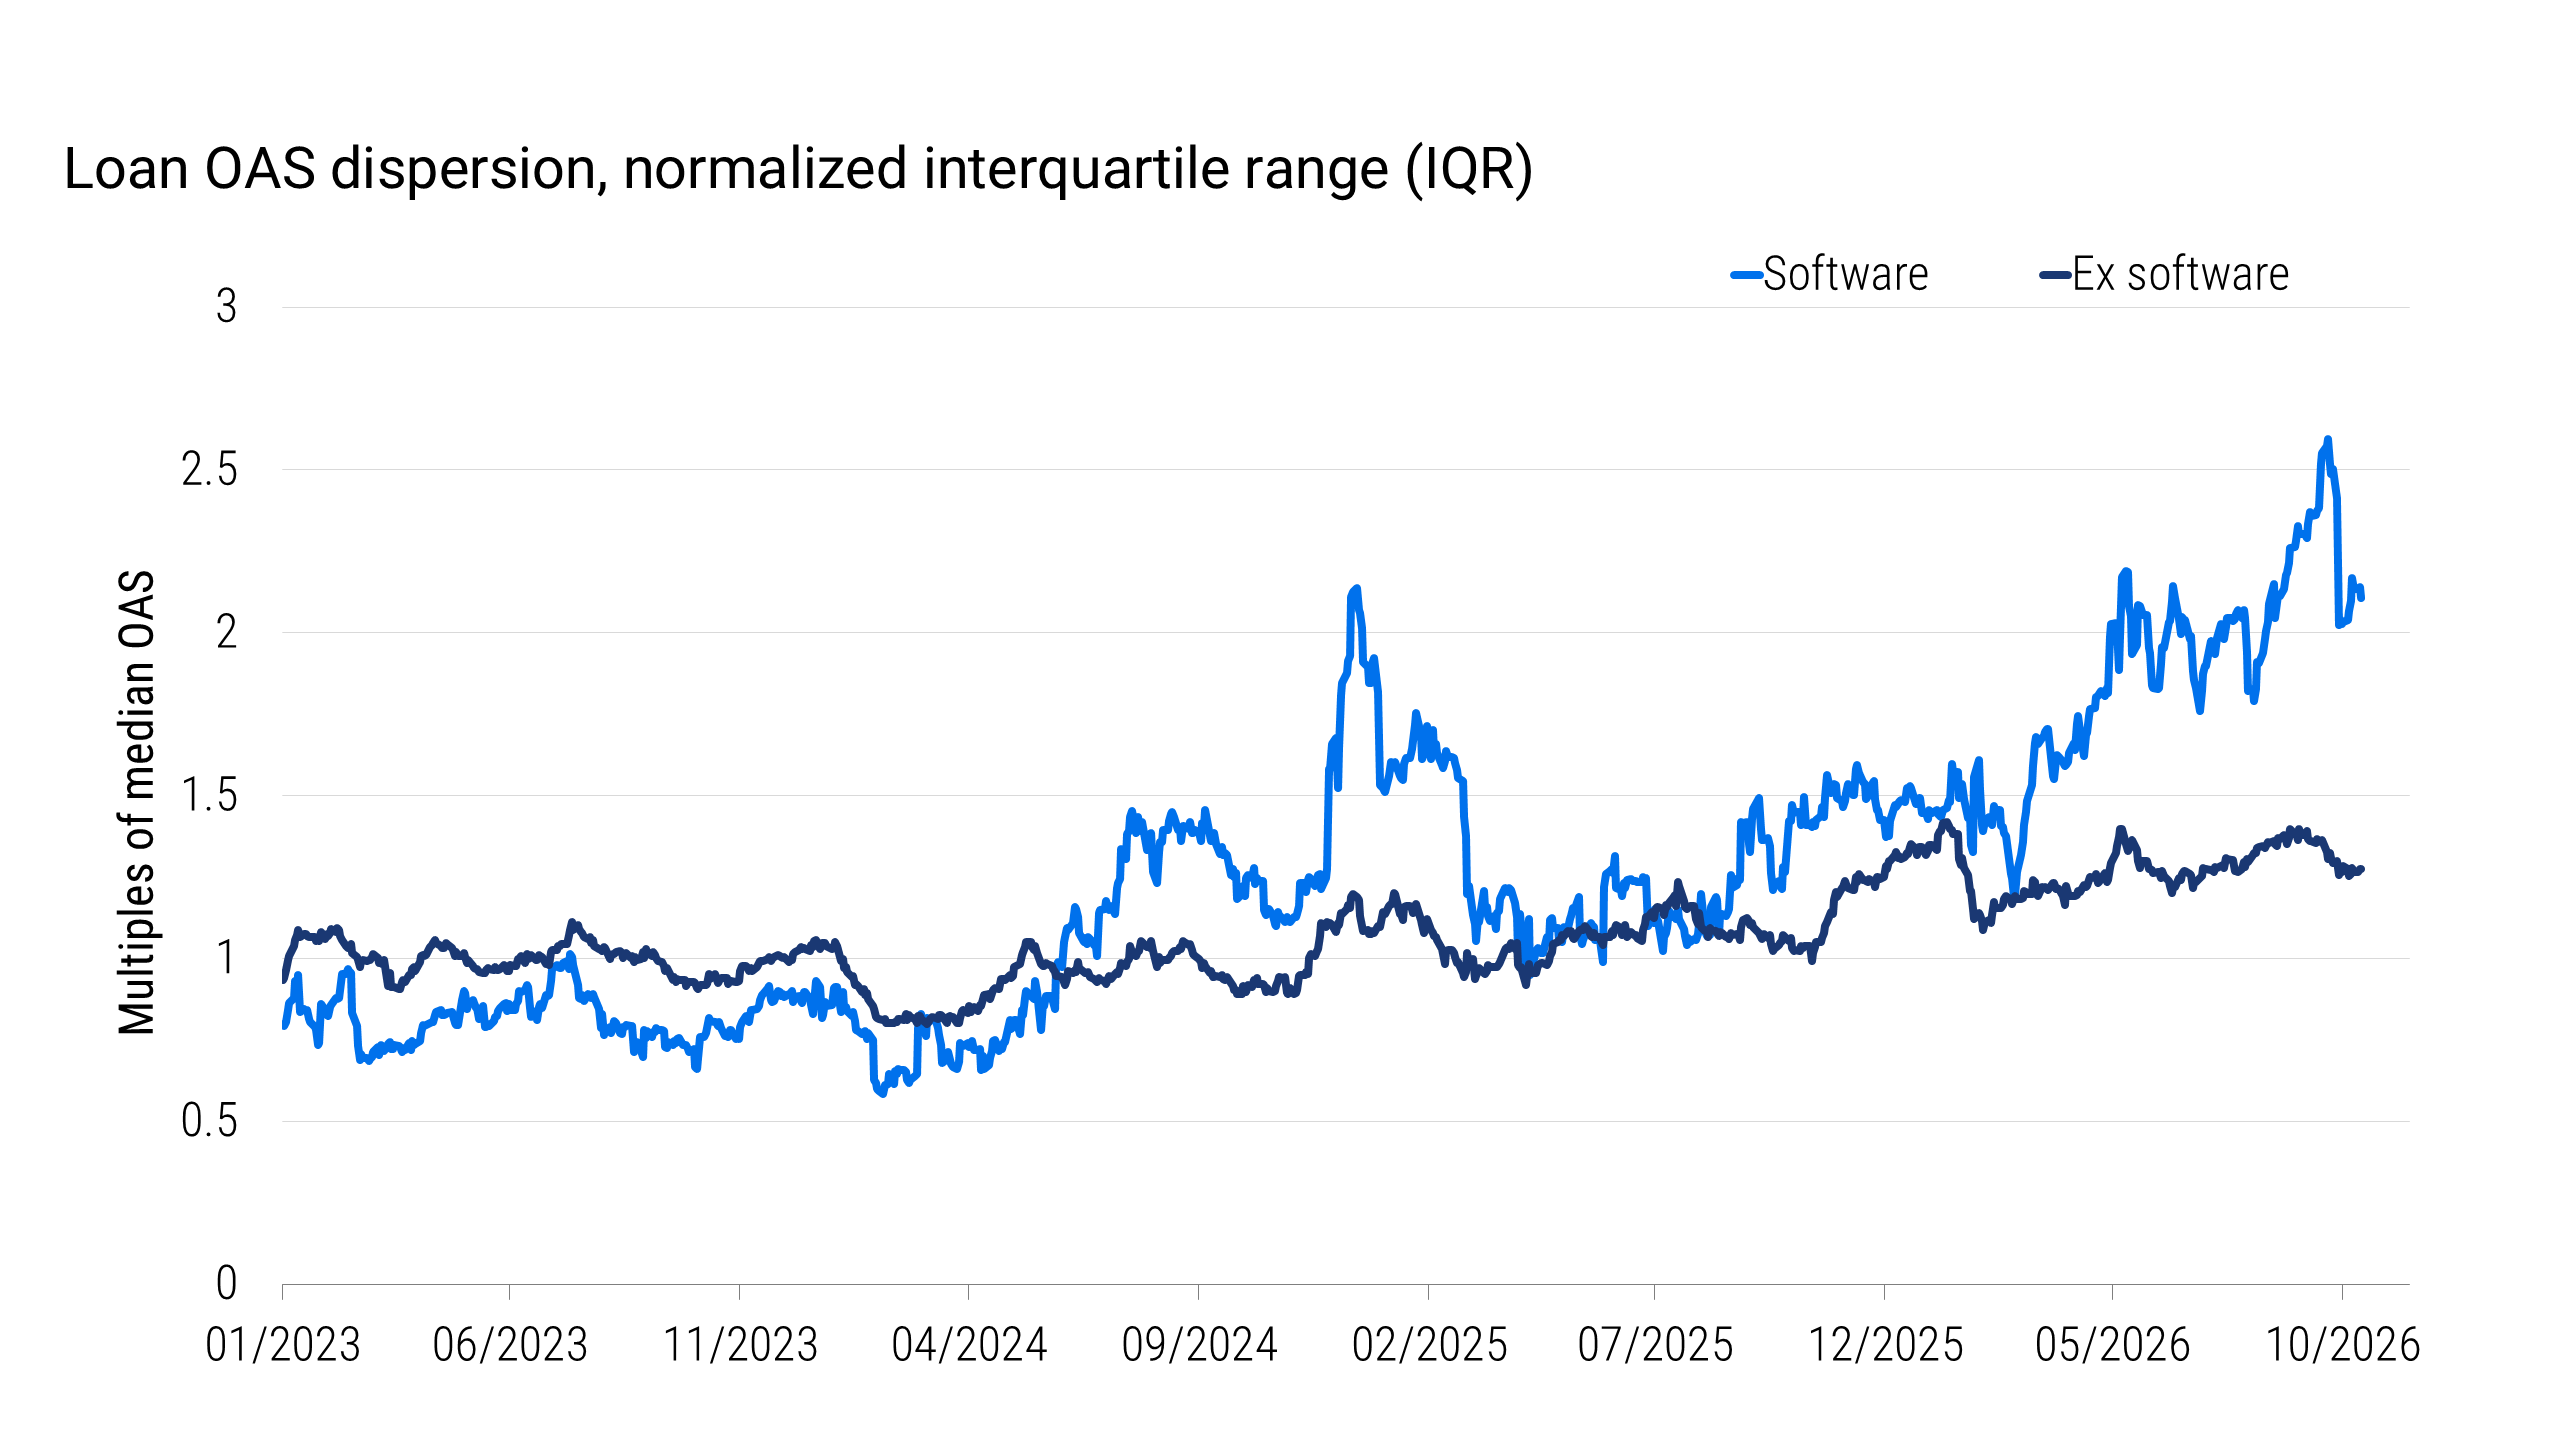
Loan investors watching this year’s trends are naturally wondering where spreads could go from here. The underlying narrative that catalyzed the sector’s relative underperformance hasn’t materially changed. A small group of issuers does appear well-positioned to benefit from the democratization of AI, as the technology’s rapid expansion rewards some software innovation. However, a much larger group of issuers faces uncertain competitive implications. Dispersion within the sector is therefore likely to remain elevated relative to last year – and also higher than in the broader loan market (see Figure 3).
Figure 3: Dispersion in software loans has increased since the AI-driven sell-off
Some issuers turn to refinancing, but at what cost?
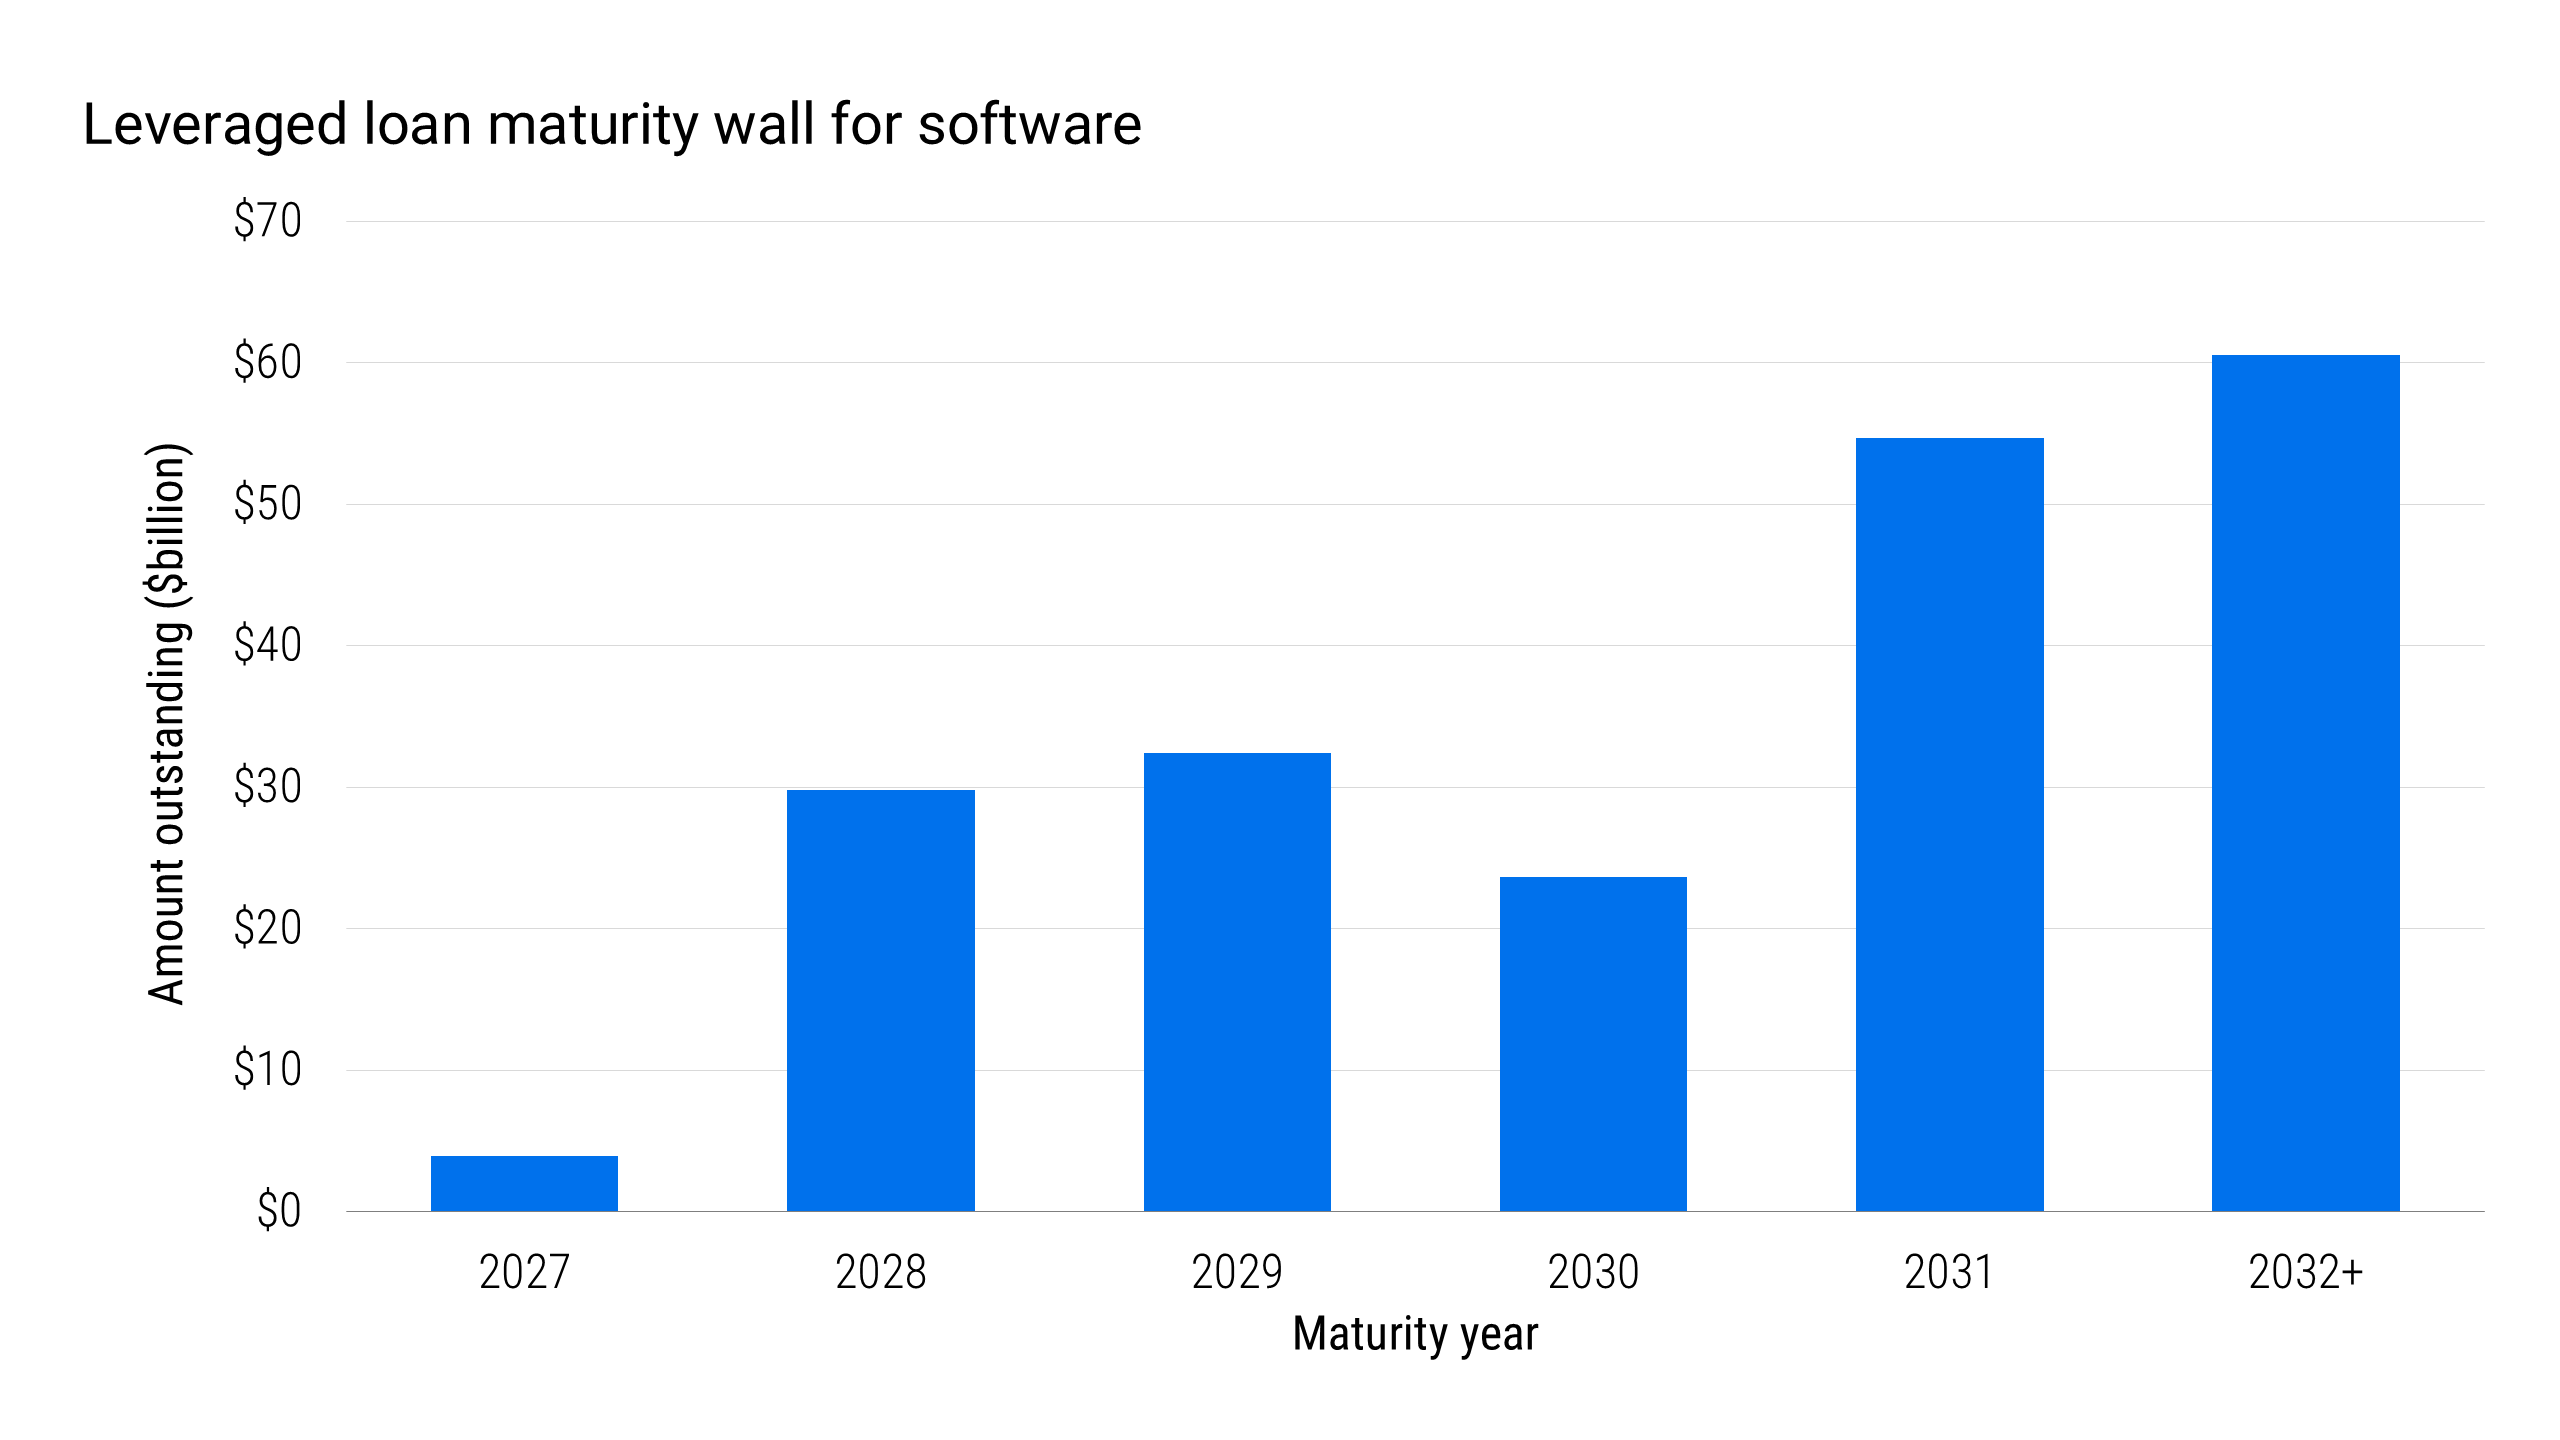
Against that backdrop, the path of least resistance remains liability management exercises (LMEs). LMEs are agreements that let issuers restructure debt in various ways, such as extending maturities or refinancing. About $62 billion of software loans are maturing in 2028 and 2029 (see Figure 4). Gaining access to attractive refinancing could matter almost as much to these issuers as navigating AI-related risks to their business models.
Figure 4: $62 billion of software loans will mature in 2028 and 2029
Recent amend-and-extend transactions show that financing options are available, but at sharply different costs depending on the issuer and situation. Some issuers that recently extended maturities were able to tap the market for just a 25-bp increase in their spread over the overnight (baseline) rate, according to PitchBook reports. Others, however, faced a spread increase of 150 bps over previous levels and had to accept a discount on their issue price, placing it below par. That range highlights how differently the market is pricing issuers based on perceived quality and resilience to AI disruption.
The takeaway is that maturity relief is available, but not always cheaply. Even after the recent rally, refinancing costs remain prohibitively expensive for many issuers relative to the borrowing costs put in place during the low-rate era.
We believe that for weaker credits, spread compression has improved the optics more than the economics. The software loan market appears to be increasingly defined by winners, losers, and wider dispersion. Until the disruptive effects of AI on software-related loan issuers become clearer, choices made during the low-interest-rate regime of yesterday are likely to drive further differentiation within the sector tomorrow.
Michael Puempel and Gabriel Cazaubieilh contributed to this report.


